
 Qamar Unnisa
A business owner says, “Sales are up, but I still feel short of cash.” The temptation is to respond with a quick explanation, a spreadsheet request, or advice about cutting expenses. A stronger response begins with curiosity. This business finance conversations guide helps coaches and advisors create the conditions for owners to understand what is happening, make sound decisions, and take responsibility for the next step.
Finance can feel personal for an owner. It may carry stress, pride, family pressure, uncertainty, or memories of previous setbacks. Yet avoiding the subject does not protect the business. A coach approach makes room for an honest conversation without positioning the coach as the person who has all the answers.
Why finance conversations require more than financial knowledge
Small business owners rarely experience cash flow, pricing, payroll, sales, operations, and personal income as separate issues. A late-paying customer may affect payroll. Underpriced work may create a full schedule with little profit. An owner who approves every purchase may be responding to a real cash concern, while also slowing the team and limiting growth.
This is why effective small business coaching combines coaching skills with an understanding of business systems. Financial results are signals from a connected system. They can reveal gaps in sales processes, policies and procedures, inventory controls, customer terms, capacity planning, or owner decision-making.
A coach does not need to become an accountant, bookkeeper, lender, or financial planner to have useful finance conversations. In fact, crossing into advice outside one’s expertise can create ethical and practical problems. The role is to help the owner notice patterns, clarify priorities, identify what information is needed, and decide where qualified financial guidance may be appropriate.
For coaches pursuing ICF-aligned practice, this distinction matters. Coaching is not about directing the client toward the coach’s preferred solution. It is about partnering with the client in a thought-provoking, accountable process. Financial literacy strengthens that partnership because it helps the coach ask more relevant questions and recognize when a concern may require referral.
Start with the owner’s relationship to the numbers
Before reviewing a report, listen for what the owner believes the numbers mean. A statement such as “We cannot afford another employee” may be a conclusion, not a verified fact. “Profit is fine” may mean the business has money in the bank at this moment, not that margins, debt obligations, and owner compensation are healthy.
You might ask, “When you say cash is tight, what are you seeing or experiencing?” Or, “Which numbers do you look at most often, and which ones do you tend to avoid?” These questions are simple, but they can reveal the owner’s current level of confidence, habits, and assumptions.
Appreciative inquiry is valuable here. Rather than beginning with what is broken, ask when the business has handled financial pressure well. What decisions helped? What routines made the numbers easier to manage? The answers may point to strengths worth restoring, such as weekly invoice follow-up, clear deposit policies, or a regular meeting with a bookkeeper.
The goal is not to make every owner love financial reports. It is to help them develop enough confidence and consistency to lead the business responsibly.
A practical structure for business finance conversations
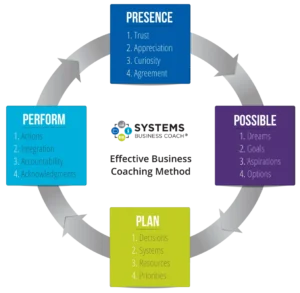
A useful conversation usually moves from context to evidence, then from choices to action. It does not need to feel scripted, but a reliable structure prevents the discussion from becoming either vague reassurance or an overwhelming review of numbers.
1. Name the decision behind the concern
Financial conversations are most productive when they serve a real decision. Is the owner deciding whether to hire, raise prices, buy equipment, take on a loan, add a service, or change customer payment terms? Without a decision, it is easy to collect data without creating movement.
Ask, “What decision are you trying to make?” Then ask what would need to be true for that decision to feel responsible. This directs attention toward useful information rather than every possible financial metric.
2. Establish the facts that matter
Invite the owner to bring current information from their accounting system, bookkeeper, accountant, or financial advisor. Depending on the decision, this could include cash on hand, accounts receivable aging, monthly revenue, gross margin, operating expenses, debt payments, payroll, or a cash-flow forecast.
Avoid interpreting reports beyond your competence. You can still ask powerful questions: “What stands out to you?” “What has changed since last quarter?” “What would you want to ask your bookkeeper about this?” A coach can help an owner prepare for a more effective conversation with a financial professional.
3. Look for system connections
Once the owner identifies a pattern, widen the view. If receivables are growing, explore the invoicing process, client agreements, collections routines, and accountability. If margins are falling, consider pricing, labor allocation, purchasing, scope changes, and delivery processes.
This is systems thinking in practice. It shifts the conversation from “How do I fix this number?” to “What in the business may be producing this result?” That distinction helps owners build an organized and profitable business rather than repeatedly treating symptoms.
4. Choose one or two next actions
A finance conversation should end with ownership and a manageable commitment. The next action may be to meet with a CPA, update a 13-week cash forecast, call overdue customers, review job costing, or test a price increase for new proposals.
Ask, “What will you do, by when, and how will you know it is complete?” If the action depends on someone else, clarify how the owner will communicate expectations and follow through. Small actions become meaningful when they establish a new operating rhythm.
Questions that create clarity without giving financial advice
Good questions are specific enough to move the conversation forward and open enough to preserve client ownership. Consider questions such as:
- What does a financially healthy month look like in this business?
- Which revenue streams are most profitable, not simply busiest?
- What is the gap between when you pay expenses and when customers pay you?
- Where do exceptions to your pricing, payment, or purchasing policies occur?
- What decision have you delayed because you do not yet trust the information?
- If this pattern continued for six months, what might it affect in the business?
- What expertise do you need around the table before you decide?
Use these questions selectively. A long list can make an owner feel examined rather than supported. The best question is often the one that responds to what the owner has just said.
Know when to refer and collaborate
A coach may help an owner think through choices, but certain matters belong with licensed or specialized professionals. Tax planning, legal structures, investment recommendations, lending terms, valuation, payroll compliance, and detailed accounting treatment may require a CPA, bookkeeper, attorney, lender, or financial advisor.
Referral is not a failure of coaching. It is part of ethical practice. The coach can help the owner identify the question they need answered, select a next step, and integrate the resulting information into a broader business decision.
Collaboration also respects the reality that financial improvement is rarely a single-person project. An owner may need clearer internal policies and procedures, better reporting from a bookkeeper, stronger sales discipline from a team member, and a more consistent leadership routine from themselves. The coach helps them see and coordinate those connections.
Common traps to avoid
The first trap is rescuing. When an owner is anxious, it can feel helpful to take over the analysis or prescribe a solution. But this may reduce the owner’s confidence and create dependence. Offer structure, questions, and practical tools while allowing the owner to think, decide, and act for themselves.
The second is treating revenue as the whole story. Revenue can be encouraging, but it does not automatically indicate profitability, available cash, or a sustainable workload. Help owners examine the measures connected to the decision at hand.
The third is using shame as motivation. Many capable owners have avoided their numbers for understandable reasons: they were busy serving customers, they never learned financial language, or prior reports were confusing. Progress is more likely when the conversation acknowledges reality without judgment.
Build financial confidence through a repeatable rhythm
One-off conversations may solve an immediate problem, but routine creates capability. An owner could establish a weekly cash review, a monthly financial meeting, and a quarterly decision conversation tied to goals and capacity. The exact rhythm depends on the business’s size, volatility, seasonality, and complexity.
Coaches can support this rhythm by asking what the owner wants to know regularly, who prepares the information, and how decisions will be documented. A simple dashboard, a recurring meeting agenda, and clear ownership may be more useful than an elaborate reporting system nobody uses.
Small Business Coach Training prepares professionals to work with these realities through a coach approach, practical small business tools, and systems-based thinking. The aim is not to turn every coach into a finance specialist. It is to equip practitioners to hold better conversations where finance, leadership, operations, and growth meet.
The next time an owner says, “I need to make more money,” pause before looking for an answer. Ask what the business is telling them, what decision is waiting, and what small, informed action they are ready to take. That is where a finance conversation can become stronger leadership.